Self-Employed Home Loans in Australia: How Lenders Actually Assess You
6 min read · Updated September 2026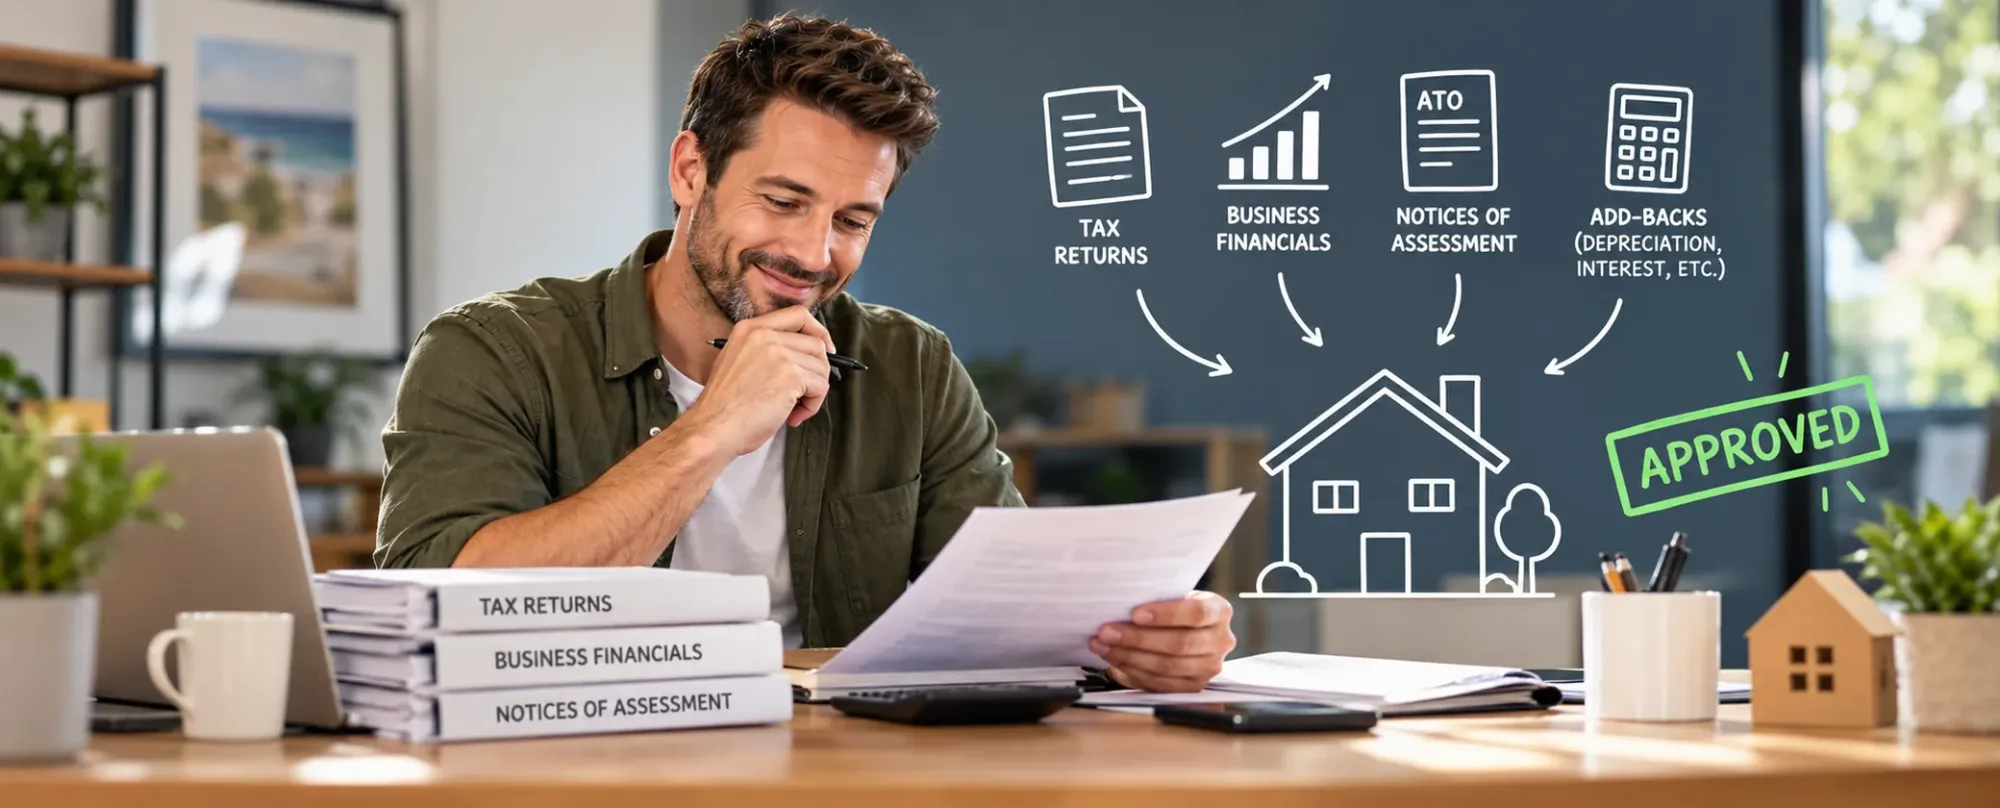
Can I get a home loan if I’m self-employed?
The simple answer is yes. Lenders approve home loans for self-employed applicants every day. However, lenders assess your income completely differently to someone earning a regular salary, and most of the time the reason self-employed clients are declined isn’t their income or whether they can afford the loan. It comes down to the choice of lender and how the application is put together.
Here is how lenders look at self-employed applicants, why they say no, and how you can make sure you are in the right position to apply from the start.
What lenders want to see from self-employed borrowers
For most lenders, the standard documents for a self-employed home loan are:
One to two years of personal tax returns and the matching Notices of Assessment from the ATO
One to two years of business tax returns and financials if you trade through a company or trust
Your ABN, usually registered for at least 18 months
The key word here is most. Every lender has different policies: some accept one year of financials, some require two, and some can even accept your BAS (business activity statements). This is why being self-employed can be a real benefit. You can match your income documentation to the lender that is going to help you achieve your goals. That said, working with a broker who understands this is just as important.
How lenders calculate self-employed income
Turnover means nothing to lenders. The first thing they look at is your net profit before tax, because this is the figure they use. Then, depending on their policy, they will use either the current year’s net profit or the average of two years, which can make a big difference to your overall loan amount. The two most important things to consider are:
1. Which years they use
A lot of lenders average your last two years of income. If your latest year is lower than the one before, most will use the more conservative figure, the lower one. If your most recent year is higher, there are lenders that will use your most recent year. The same set of financials can produce very different results and very different borrowing power.
2. Add-backs
Most self-employed borrowers get this wrong, and it severely impacts their borrowing capacity. Add-backs are expenses you’ve declared that reduce your taxable income but don’t reflect actual spending, and lenders can add them back to your income. The most common ones include:
Depreciation
Interest
One-off expenses that won’t repeat, like a legal bill or a big equipment repair
Extra super contributions above the compulsory amount, with some lenders
Here’s a simple illustration of how much it can change the picture:
Amount | |
|---|---|
Net profit on tax return | $60,000 |
Add back: depreciation | $15,000 |
Add back: interest | $5,000 |
Add back: one-off legal fee | $8,000 |
Income a lender may assess | $88,000 |
That has taken the income a lender can assess from $60,000 to $88,000 just by applying the right add-backs and showing more income on paper, all without earning a dollar more or paying more tax. Not every lender accepts every add-back, and you need your accountant to evidence each one. But it can often be the difference between a no and a yes.
Why banks knock back self-employed borrowers (and what fixes it)
Most self-employed knock-backs aren’t about affordability. They come from one of these five:
Why they said no | What usually fixes it |
|---|---|
Your tax return shows low income because your accountant did what you asked and minimised tax | Add-backs, a lender that assesses your most recent year, BAS statements, or timing the application around your next return |
You had a lower income year (a lost contract, a slow start) | Choosing a lender that can look beyond a single lower income year and understands the business and its fluctuations |
You have ATO debt | Some lenders are fine with it if you’re on a payment plan and keeping to it, and some will even refinance it |
Your business structure is complicated (company, trust, income through dividends or distributions) | A lender that accepts your structure and the way income flows through it |
You chose the wrong lender | Choosing the lender whose policy fits you, before you apply |
That last one is the biggest issue we see. The bank that holds your business account isn’t automatically the right bank for your home loan. It comes down to policy. If you pick the wrong one and get a no, it can have nothing to do with you, but how are you to know?
It matters more than people think, because every rejected application leaves a credit enquiry on your file. Apply to three banks yourself, get three no’s, and the fourth lender now has a harder decision.
Full doc vs low doc vs 1-year loans
There are three main ways to get a self-employed home loan. Here’s how they compare:
Full doc | Low doc | 1-year / newer ABN | |
|---|---|---|---|
Who it’s for | Two or more years of returns lodged | Returns not lodged, or they don’t show real income | Recently went out on your own |
What you provide | Tax returns, Notices of Assessment, financials | BAS, business bank statements, accountant’s declaration | One year of returns, plus proof of experience in your industry |
Choice of lenders | Widest | Narrower, often specialist lenders | Narrower, but growing |
Rate and deposit | Usually a higher rate and a bigger deposit | Often standard pricing if you qualify |
Full doc gets you the best deals, so it’s where most people should start. Low doc and 1-year loans are good tools, but only when they’re genuinely the right fit.
Real example: two bank rejections, then approved
A client of mine came to me after two banks had already said no. His sole trader business had been trading for 18 months.
Why he got knocked back: The two banks he went to first averaged his income over two years, in line with their policy. He only had one year’s income on a tax return.
What we did differently: We identified lenders that accepted 12 months of income, which boosted his borrowing capacity.
The result: He was approved to purchase a $1m property, compared to the other lenders that said he could only purchase a $600,000 property.
Nothing about his business changed between the no and the yes. The only difference was how the application was put together and where it went.
Self-employed home loan FAQs
How many years of tax returns do I need for a home loan if I’m self-employed?
Most lenders ask for two years. Some accept one year, especially if you worked in the same industry before going out on your own.
Do lenders use my turnover or my profit?
Your net profit before tax. Lenders start with your taxable income or net profit, then adjust it with add-backs like depreciation and one-off expenses.
Can I get a home loan with an ATO debt?
Often, yes. Many lenders will consider it if you’re on a payment plan and keeping to it. Some will even refinance the ATO debt into the home loan.
Is it harder to get a home loan when you’re self-employed?
Yes, because of the complexity and the way lender policies vary. However, when you partner with someone who knows the right lenders, it’s very straightforward. Approval depends heavily on which lender you use and how your income is presented.
Should I lower my tax or keep my income high if I want a loan?
That’s a conversation to have with your accountant and your broker together, ideally 6 to 12 months before you apply. Tax planning and loan planning pull in different directions, so the timing matters. Once you’re ready, pre-approval tells you where you stand before you make an offer.
The bottom line
Being self-employed doesn’t make you a bad borrower. It makes you a borrower who needs the right lender and a properly built application.
Which lender and which loan are right for you depends on your situation. That’s what I do. If your bank has said no, or you’re not sure where you stand, book a free chat with me and we’ll work out your options.
About the author: Luke Patterson is a mortgage broker and a director of Koalify. He’s self-employed himself, and specialises in home loans for business owners, sole traders and contractors with complex income.
This article is general information only and doesn’t consider your personal objectives, financial situation or needs. It isn’t tax or financial advice. Speak to your accountant about tax, and to a broker about your specific lending situation.
Related guides
Compare rates from multiple lenders online.
Let our mortgage brokers secure the most suitable deal for you.